Money often looks organized from the outside while quietly creating tension underneath. Many people pay bills on time, avoid obvious debt issues, and still feel uneasy when opening banking apps. That discomfort usually comes from irregular attention rather than financial failure, which makes money feel unpredictable instead of manageable.
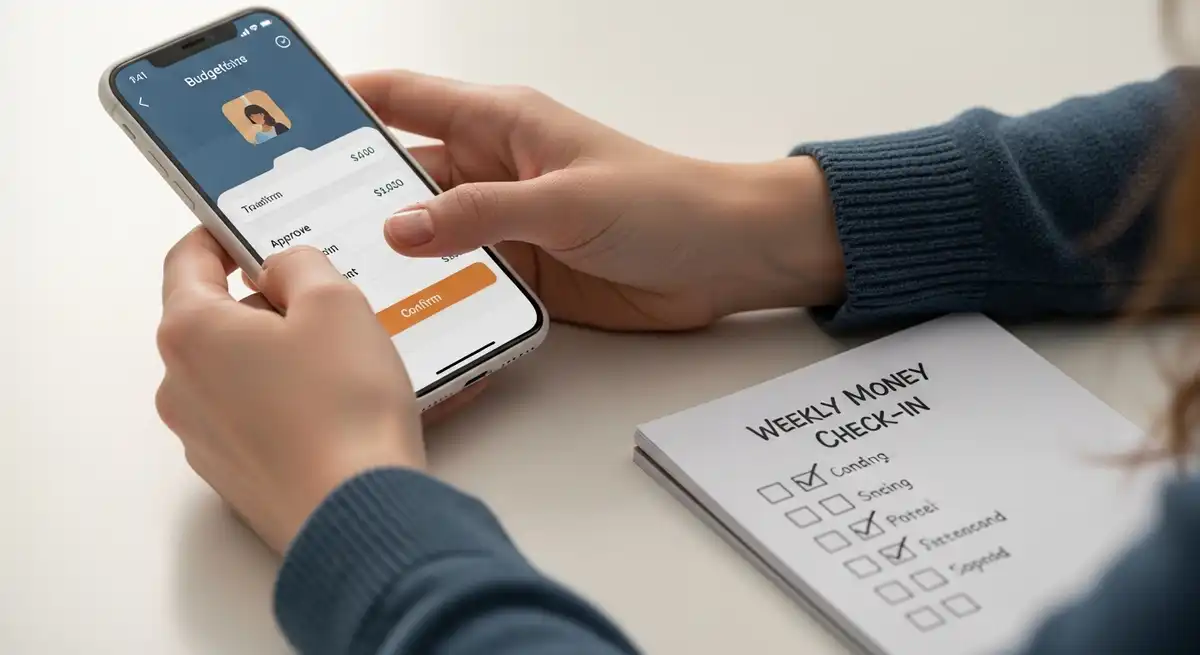
In everyday households, money moves quickly through digital payments, subscriptions, and shared responsibilities. When finances are only reviewed during emergencies or deadlines, the body starts to associate money with urgency and self-criticism. A simple weekly money check-in replaces that pattern with steadiness, helping money feel like a regular life task rather than a looming problem.
The simple weekly money check-in that changed everything is not a budgeting overhaul or productivity system. It is a brief, repeatable ritual that keeps finances within calm awareness. Over time, attention replaces anxiety, and familiarity replaces fear, which supports confidence without requiring financial expertise.
Weekly money check changed: Understanding the core idea of a weekly money check-in
A weekly money check-in is a short, scheduled review of personal or household finances focused on awareness rather than judgment. It usually involves reviewing recent spending, noting upcoming obligations, and acknowledging near-term plans. The goal is orientation, not fixing every detail or achieving perfect numbers.
Wellness educators often point out that predictability reduces stress responses in daily life. When money is reviewed at a consistent time, the brain receives fewer surprise signals. This steady rhythm supports calmer thinking and reduces the emotional charge attached to financial information.
In everyday use, a weekly money check-in acts as a gentle point of contact. It allows patterns to be noticed early and adjustments to happen gradually. Many people find that finances feel lighter simply because they are no longer avoided.
Why reactive money habits create ongoing stress
Reactive money habits form when finances are only addressed during urgent moments. These moments include overdraft alerts, unexpected bills, or sudden realizations that spending went off track. Over time, this pattern trains the nervous system to stay on edge around money.
Stress awareness research shows that uncertainty often feels more distressing than known challenges. When money is ignored until something feels wrong, uncertainty builds quietly. Even stable finances can start to feel unsafe because the information arrives too late.
In daily routines, reactive habits make money feel unpredictable and overwhelming. Regular weekly check-ins replace reaction with anticipation. This shift supports steadier emotions and makes financial decisions feel more intentional and grounded.
The psychological role of predictability in financial wellbeing
Predictability plays a key role in emotional regulation. When the brain knows when information will be reviewed, it reduces the sense of threat. A weekly money check-in creates that structure by setting a clear expectation around financial attention.
Lifestyle guidance often highlights routine as a stabilizing force. Just as consistent meal or sleep times support physical balance, consistent financial reviews support mental steadiness. The content of the review matters less than the regular return to it.
In practical terms, predictability makes money feel familiar rather than intimidating. Repeated exposure in a calm setting reshapes emotional associations. Many people notice that finances feel less charged simply because the timing is no longer random.
Setting the environment for a supportive money ritual
A weekly money check-in works best when treated as a ritual rather than a performance review. The environment should signal comfort and neutrality, not pressure. This might mean sitting in a familiar place, using soft lighting, or pairing the activity with a calming drink.
Wellness educators often emphasize how environment influences habit consistency. Comfortable settings reduce resistance and increase follow-through. When money reviews feel physically safe, mental resistance tends to soften naturally.
In everyday contexts, people adapt this ritual to fit their lives. Some choose quiet mornings, others prefer evenings after work settles. What matters is creating an atmosphere that supports attention without judgment.
Regulating the nervous system before reviewing finances
Before opening financial apps or statements, brief grounding actions can help settle the body. Common options include slow breathing, placing feet firmly on the floor, or relaxing the jaw and shoulders. These signals tell the nervous system that there is no immediate danger.
Stress research shows that regulated physical states support clearer thinking. When the body is calmer, numbers are processed more objectively. This reduces the likelihood of spiraling thoughts or emotional reactions during reviews.
With repetition, this preparation becomes automatic. Over time, the body learns that money review equals safety and clarity. This association supports long-term consistency with financial habits.
The three-question framework that guides each check-in
The first guiding question looks at what actually happened during the past week. This step focuses on reviewing transactions and spending patterns without interpretation. Accuracy comes before analysis, which keeps the process grounded.
The second guiding question looks ahead to the coming week. By noticing known events and needs, spending becomes intentional instead of reactive. This supports alignment between daily choices and personal priorities.
The third guiding question scans for near-future needs. Looking thirty to ninety days ahead highlights irregular expenses that often cause stress when forgotten. This step supports preparedness without overplanning.
Looking back with clarity rather than judgment
Reviewing past spending replaces assumptions with facts. Many people are surprised by small, repeated expenses that quietly add up. Seeing these patterns early supports informed decisions without emotional intensity.
Lifestyle educators often note that neutral observation reduces defensiveness. When spending is treated as data instead of failure, learning becomes possible. This mindset supports curiosity rather than self-criticism.
In daily practice, this review remains brief and factual. It creates a clear foundation for planning without lingering on mistakes.
Choosing intentionally for the coming week
Looking ahead shifts attention from correction to choice. By identifying upcoming meals, social plans, or obligations, spending decisions feel less rushed. This reduces impulsive choices driven by convenience.
Intentional planning is linked to lower decision fatigue. When choices are made ahead of time, daily life feels smoother. This supports both financial awareness and emotional balance.
In practice, many people choose one or two priorities for the week. Keeping intentions simple makes them easier to follow.
Supporting future needs without anxiety
Future-focused scanning helps prevent mental double counting. This happens when the same money is mentally assigned to multiple future expenses. Clarifying assignments reduces confusion and surprise stress.
Wellness guidance often encourages realistic planning over optimistic assumptions. Acknowledging upcoming costs builds honesty without alarm. This supports trust in personal decision-making.
Over time, this step becomes easier. As future expenses become familiar, they lose emotional weight.
The fifteen-minute structure that keeps the habit sustainable
A weekly money check-in usually fits within fifteen minutes. This clear boundary reduces resistance and prevents overthinking. Short sessions are easier to repeat consistently.
The first minutes focus on settling the body and reviewing balances. This provides orientation without overwhelming detail. Quick awareness supports confidence.
The remaining time involves categorizing transactions and scheduling upcoming bills. Ending the session calmly reinforces completion and emotional safety.
Addressing frictionless spending in digital environments
Digital payments reduce the physical experience of spending. Without sensory cues, money can feel abstract. This often leads to unnoticed increases in everyday purchases.
Weekly reviews shorten the feedback loop. Seeing patterns within days instead of weeks allows small adjustments. Awareness restores a sense of choice.
In daily life, simple changes such as alerts or removing saved cards can support the weekly ritual. These tools encourage awareness without restriction.
Why weekly reviews often feel easier than monthly ones
Monthly financial reviews can feel heavy due to the volume of information. Weekly reviews spread attention evenly across time. This lowers emotional load.
Behavioral research links frequent feedback with steadier outcomes. Smaller corrections feel more manageable than large resets. This supports consistency.
In practical routines, weekly reviews blend more easily into busy schedules. They feel approachable rather than overwhelming.
Integrating automation without losing awareness
Automation handles predictable expenses like bills or savings transfers. When systems are in place, weekly reviews become monitoring rather than management. This reduces effort while preserving clarity.
Lifestyle balance guidance often suggests pairing structure with flexibility. Automation offers structure, while check-ins allow adjustments. Together, they support sustainability.
Many people notice that automation frees mental energy. Weekly reviews then focus on exceptions rather than routine tasks.
Parenting and working-life relevance of weekly money rituals
Parents and working caregivers juggle many responsibilities. Financial uncertainty adds unnecessary strain. A weekly money check-in offers a stable point of orientation.
Family routines benefit from predictability. When finances are reviewed regularly, conversations stay calmer and more collaborative. This supports shared responsibility.
In working households, the ritual helps plan around school schedules, childcare, and variable expenses. It integrates money awareness into real-life demands.
Using a money date approach in shared households
Shared finances benefit from structured conversations. A money date frames financial reviews as collaborative rather than corrective. This reduces tension.
Relationship education often highlights shared rituals for alignment. Regular financial check-ins normalize open discussion and transparency. Trust builds gradually through repetition.
In everyday use, these sessions remain brief and focused. Ending with shared intentions supports connection rather than conflict.
Frequently Asked Questions
How often should bank accounts be reviewed for everyday awareness
Bank accounts are commonly reviewed weekly to balance awareness and emotional ease. This frequency helps people notice unusual activity and understand spending patterns without constant monitoring. Many find that weekly reviews fit naturally into routines and support steady engagement without increasing anxiety.
What a weekly money date usually involves
A weekly money date involves reviewing recent spending, planning upcoming expenses, and acknowledging future needs. The focus stays on shared understanding rather than correction. This structure supports calm conversations and consistent financial awareness in everyday life.
Why looking at finances often triggers discomfort
Discomfort around finances is often linked to unpredictability and past stress. When money is only reviewed during problems, the brain associates it with threat. Regular, calm reviews gradually change that association and support emotional neutrality.
How budgeting apps fit into weekly reviews
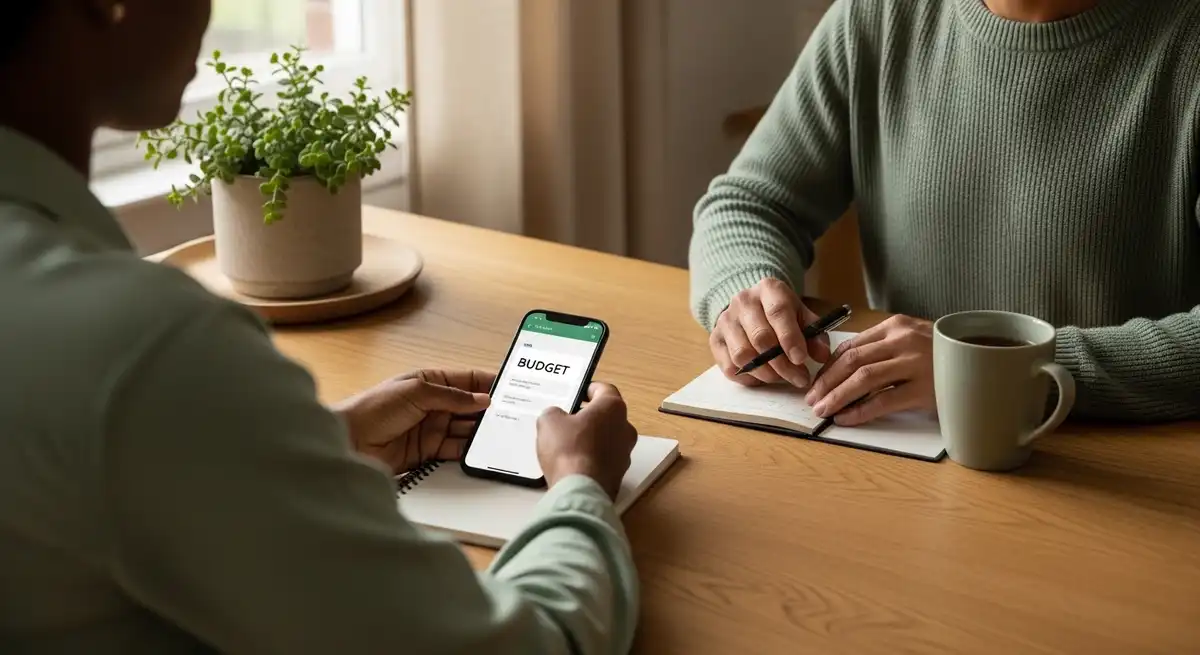
Budgeting apps support organization and visibility during weekly check-ins. They centralize information and reduce manual effort. Many people choose tools that feel intuitive rather than complex, since ease of use supports consistency.
What fake math means in everyday budgeting
Fake math refers to mentally assigning the same money to multiple future expenses. This creates confusion and surprise stress. Clarifying assignments during weekly reviews supports realistic planning and reduces uncertainty.
Why high earners still feel financial pressure
High earners often manage complex expenses and variable commitments. Without regular reviews, money can feel unaccounted for despite sufficient income. Weekly check-ins increase clarity and restore a sense of control.
How weekly reviews support long-term goals
Weekly reviews keep goals visible through small, consistent attention. This supports gradual progress rather than sporadic effort. Many people find this approach easier to maintain over time.
Whether weekly check-ins replace professional advice
Weekly check-ins are a lifestyle support tool, not professional financial guidance. They complement, not replace, advice from qualified professionals. This practice supports awareness and preparedness.
What happens when a week is missed
Missing a week is common and does not undo progress. The practice focuses on rhythm rather than streaks. Returning gently supports sustainability.
How long it takes to feel more comfortable with money reviews
Comfort often increases gradually over several weeks. Familiarity reduces emotional charge. Consistency matters more than intensity.
A calm editorial conclusion
The simple weekly money check-in that changed everything works because it restores a steady relationship with money. Through regular, calm attention, finances become familiar and manageable. This approach supports clarity and trust without pressure, offering a realistic way to include money as a normal part of everyday life.
Medical Disclaimer
This content is for informational purposes only and does not constitute medical or mental health advice. It does not diagnose, treat, cure, or prevent any condition. Always consult a qualified healthcare professional for personal health concerns or before making lifestyle changes.
For wider background on this, see the American Psychological Association on stress.