Money management often shows up quietly in daily life, shaping stress levels, sleep quality, and household stability without much notice. For many people, budgeting feels emotionally loaded because it intersects with safety, family needs, and long term responsibility. Approaching budgeting as self-care reframes it as a supportive lifestyle practice that helps reduce uncertainty and emotional strain over time.
A budget that feels like self-care is not designed to control behavior or force perfection. It focuses on creating predictability, protecting essential needs, and allowing intentional spending without guilt. This approach supports emotional steadiness by turning money planning into a quiet system that works in the background. When budgeting aligns with real life, it becomes easier to maintain and less mentally exhausting.
Create budget feels self: Understanding Why Money Stress Feels So Personal
Money stress feels personal because finances are closely tied to basic security such as housing, food, education, and healthcare. When these needs feel uncertain, the body often stays in a state of alert, which can increase tension and mental fatigue. This response is not a personal failure, it is a common reaction to perceived instability.
Daily responsibilities often compound financial stress. Managing bills alongside work, caregiving, and household planning leaves little room for emotional recovery. Without a clear system, even small financial decisions can feel overwhelming. A self-care oriented budget reduces this load by offering structure and clarity.
Social expectations also shape how people experience money. Cultural messages often link financial success to personal worth, which can create shame during difficult periods. Removing moral judgment from budgeting allows financial planning to exist as a practical skill rather than a measure of value.
Budgeting as a Form of Lifestyle Support
Budgeting as self-care prioritizes stability over restriction. Instead of focusing on what must be cut, it emphasizes what needs to be supported. This shift allows budgeting to function as a planning tool that reduces daily stress rather than adding to it.
Predictability plays a key role in emotional wellbeing. Knowing when bills are covered and savings are set aside creates a sense of order. This does not remove financial challenges, but it softens their emotional impact and supports calmer decision making.
A lifestyle focused budget also respects limited time and energy. Many people manage work, family, and personal responsibilities with little margin. Simplifying financial choices helps preserve mental energy for other areas of life.
Moving Away From Shame-Based Financial Habits
Shame based budgeting relies on self criticism to drive change. Missed goals or unexpected spending are framed as failures, which often leads to avoidance. Over time, this pattern reduces engagement and increases stress.
A self-care approach replaces judgment with observation. Spending patterns are viewed as information shaped by real circumstances. This makes it easier to adjust plans calmly and realistically.
Forgiveness supports consistency. Financial situations are influenced by health, caregiving, and economic conditions. Recognizing these factors allows budgeting to adapt without emotional overload.
Separating Self-Worth From Financial Outcomes
Income and savings often fluctuate across life stages. When financial outcomes are tied to identity, stress increases during change. Separating self-worth from numbers helps stabilize emotional responses.
Focusing on systems rather than outcomes supports resilience. A budget that covers essentials and allows gradual progress is more sustainable than chasing perfect figures. This perspective supports long term wellbeing.
When money decisions are not moralized, planning feels more neutral. This encourages consistent engagement and reduces fear around reviewing finances.
Connecting With the Future Self
Future self-continuity refers to how connected a person feels to their future needs. When the future feels distant, saving becomes harder. A self-care budget makes future needs more tangible.
Visualizing specific future scenarios helps align present choices. Savings can be framed as care for future stability rather than loss today. This perspective supports patience without pressure.
Strengthening this connection encourages consistency. Planning becomes an act of support rather than sacrifice, which reduces resistance over time.
Understanding Immediate Gratification Without Judgment
Immediate gratification is common during stress. Short term comfort often feels necessary when energy is low. Recognizing this pattern removes blame.
A self-care budget plans for enjoyment rather than ignoring it. Including intentional spending reduces the likelihood of impulsive decisions driven by fatigue.
When enjoyment is expected and planned, spending tends to become more mindful. This balance supports emotional regulation and financial steadiness.
Choosing a Flexible Budgeting Structure
No single budgeting method fits every situation. Flexibility allows budgets to respond to changing needs without failure. A supportive structure adjusts with life.
Percentage based frameworks offer guidance without micromanagement. They provide direction while allowing personal priorities. This balance supports sustainability.
Seasonal changes and family needs also require adjustment. A flexible budget anticipates variation and reduces stress around unexpected costs.
Using the 50 30 20 Framework With Compassion
The 50 30 20 framework offers a simple reference for needs, wants, and savings. Its value lies in clarity, not precision. When used compassionately, it supports balance.
Many households adjust percentages to reflect real costs. The framework remains helpful as long as it reduces mental strain. It is a guide, not a rule.
Progress matters more than alignment. Even partial use increases awareness and emotional steadiness.
Exploring Conscious Spending for Emotional Clarity
Conscious spending focuses on intention rather than restriction. Essentials and savings are addressed first, allowing remaining funds to be used without guilt.
Automation supports this approach by reducing daily decisions. When priorities are handled automatically, stress decreases.
This structure provides mental clarity. Knowing that core needs are covered allows spending to feel calmer and more deliberate.
Adjusting Budgets Across Life Stages
Life stages influence financial priorities. Parenting, health changes, and career shifts require adaptation. A self-care budget responds without judgment.
Regular reviews support relevance. Adjustments based on real experience keep budgets supportive rather than rigid.
This adaptability strengthens resilience during uncertainty. Planning remains possible even when outcomes change.
Understanding Guilt-Free Spending
Guilt-free spending acknowledges enjoyment as a valid need. It removes the cycle of deprivation and overcorrection. This supports emotional balance.
Planned enjoyment reduces impulsive spending. Permission within structure builds trust with financial systems.
Intentional choices replace reactive behavior. Spending aligns with values rather than stress responses.
Using a Joy-Based Ledger for Awareness
A joy-based ledger tracks emotional satisfaction after purchases. This builds awareness without criticism. Patterns emerge over time.
Some expenses consistently add value, others do not. This insight guides future choices gently.
The practice centers personal experience. Awareness grows without pressure or restriction.
Mental Accounting as a Stress Reduction Tool
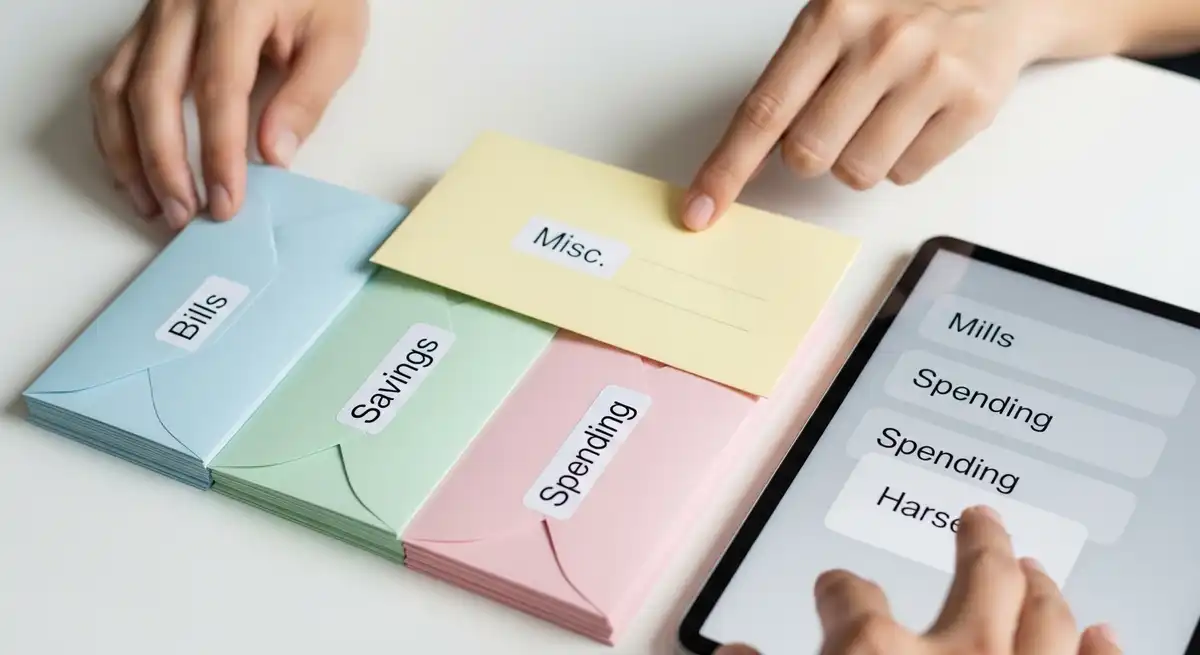
Mental accounting separates money into clear categories. This reduces cognitive load and confusion. Clarity supports calm decision making.
Separate accounts for bills, savings, and spending are common. This structure limits constant recalculation.
Clear boundaries reduce emotional charge around money. Decisions feel simpler and less stressful.
Automating Financial Care
Automation removes reliance on willpower. Savings and bills are handled consistently. This supports stability during busy periods.
Aligning automation with income timing improves consistency. Financial care becomes routine.
Mental energy is preserved. This is especially helpful for caregivers and working parents.
Building an Emergency Fund for Emotional Security
An emergency fund buffers uncertainty. It provides reassurance during unexpected expenses. Emotional resilience improves with preparedness.
Any amount contributes to stability. Starting small builds confidence.
Fear decreases when surprises feel manageable. This supports calmer responses.
Planning for Irregular Expenses With Sinking Funds
Sinking funds prepare for predictable irregular costs. Small regular contributions reduce impact. Stress decreases.
Expenses feel anticipated rather than disruptive. Planning replaces reaction.
This approach supports smoother cash flow and reduces debt reliance.
Insurance as Preventive Lifestyle Planning
Insurance transfers risk away from daily finances. Coverage supports long term stability. Anxiety decreases.
Regular review ensures relevance. Life changes often require updates.
Protection limits financial shock. Peace of mind increases.
Mindful Budget Reviews as a Routine Practice
Budget reviews work best as neutral check-ins. Evaluation without judgment supports consistency. Stress stays lower.
Monthly reviews balance awareness and effort. Adjustments reflect real life.
Confidence grows through familiarity. Budgeting becomes routine.
Budgeting During Economic Uncertainty
Uncertainty increases stress. A self-care budget focuses on controllable factors. Agency is preserved.
Essentials take priority. Temporary adjustments are practical, not failures.
Clear household communication reduces conflict. Shared understanding supports stability.
Parenting and Budgeting as Emotional Labor
Parents carry added financial responsibility. Decisions affect family stability. Stress can intensify.
Predictable systems support caregiving. Mental space increases.
Calm approaches model healthy money habits. Fear is reduced.
Budgeting for Working Mothers and Caregivers
Working mothers manage competing demands. Time and energy are limited. Simplicity matters.
Automation and flexibility support continuity. Financial care continues during busy periods.
Realistic expectations reduce pressure. Sustainability matters more than optimization.
Cultural and Social Contexts of Money Management
Money habits reflect culture and history. Expectations vary widely. Self judgment decreases with awareness.
A self-care approach respects context. Personal values guide choices.
Budgeting becomes personal, not prescriptive. Inclusivity improves.
Fully Expanded Frequently Asked Questions
Is budgeting a form of self-care
Budgeting can function as self-care when it reduces uncertainty and supports emotional stability. It becomes supportive when designed to protect essential needs and allow intentional enjoyment. This approach emphasizes clarity and consistency rather than restriction or self-criticism.
How can someone start budgeting when feeling overwhelmed
Starting with observation is often helpful. Tracking expenses briefly without judgment builds awareness without pressure. Small automated steps can then be added gradually to support consistency.
Why does budgeting often increase anxiety
Budgeting increases anxiety when linked to shame or fear of failure. Rigid rules can amplify stress. Supportive structures and neutral language reduce emotional activation.
What is value-based budgeting
Value-based budgeting aligns spending with personal priorities. It focuses on intentional choices that support daily life. Satisfaction often increases and guilt decreases.
How can guilt around spending be reduced
Guilt lessens when enjoyment is planned. Discretionary categories acknowledge human needs. Awareness replaces judgment.
How much should be saved in an emergency fund
Guidance often suggests several months of essentials. Any amount helps. Progress matters more than speed.
What budgeting method is most realistic
The most realistic method fits current circumstances. Flexibility supports consistency. Sustainability matters.
How does money stress affect wellbeing
Financial stress is linked with sleep disruption and fatigue. Reducing uncertainty supports wellbeing. Predictable systems help.
Can budgeting help reduce impulse spending
Supportive structures reduce impulse spending. Automation and planned enjoyment limit reliance on willpower.
How often should a budget be reviewed
Monthly reviews are common. They allow adjustment without constant monitoring. Mental energy is preserved.
Conclusion
Learning how to create a budget that feels like self-care reframes financial planning as a supportive lifestyle practice. When budgeting prioritizes clarity, predictability, and compassion, it reduces stress rather than adding to it. This approach supports long term wellbeing by aligning money management with real responsibilities and emotional limits.
Medical Disclaimer
This content is for informational purposes only and does not constitute medical advice. It does not diagnose, treat, cure, or prevent any condition. Consult a qualified healthcare provider before making health, mental wellbeing, or lifestyle changes, especially if you have existing medical conditions or concerns.
For wider background on this, see the National Heart, Lung, and Blood Institute on sleep.