Money stress often builds quietly through small, repeated moments of avoidance rather than major financial mistakes. Many people juggle work, family, and household demands while managing finances only when something goes wrong. A predictable, limited weekly routine helps keep money organized without taking over mental space or emotional energy.
For working parents and caregivers, financial attention competes with many urgent priorities. When money management feels endless or unclear, it tends to slip down the list. A structured one hour each week creates a boundary around financial care, allowing it to stay consistent without becoming overwhelming or intrusive.
This approach treats financial organization as a lifestyle habit rather than a discipline test. It focuses on clarity, automation, and steady routines that fit into real life. Over time, this structure supports calmer decision making and reduces the background stress often associated with money.
Simplify finances hour week: Understanding the One-Hour Financial Framework
How to simplify your finances with one hour a week means reserving a specific, repeatable time to review financial systems. This hour is not for constant adjustments or self criticism, but for observing what is working and noticing what needs light attention. Many people find this predictable rhythm easier than sporadic financial check ins.
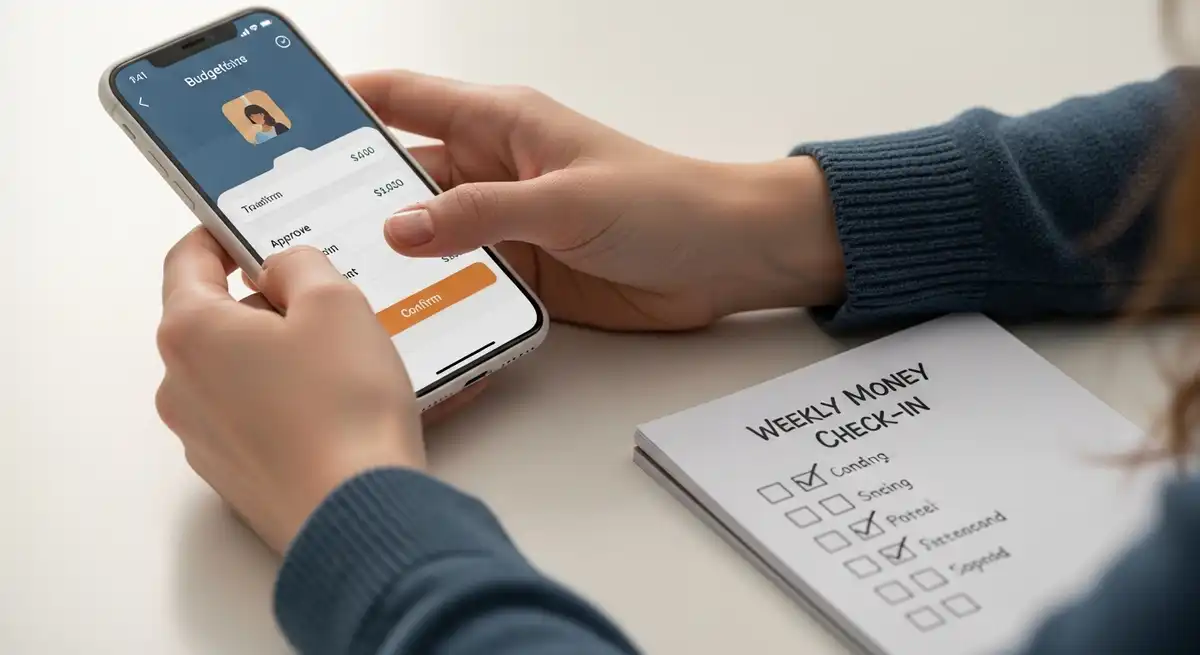
The framework relies on preparation rather than reaction. Most bills, savings, and transfers run automatically, so the weekly hour is mainly for confirmation. This reduces the mental effort of remembering deadlines and helps prevent small issues from becoming stressful surprises.
Over time, this routine builds familiarity with personal financial patterns. Knowing what to expect each week often reduces anxiety and avoidance. The result is steadier engagement without the pressure of constant monitoring.
Why Financial Complexity Leads to Inaction
Financial complexity often creates emotional resistance instead of motivation. When accounts, passwords, and obligations feel scattered, many people delay engagement to avoid discomfort. Research in behavioral science shows that too many choices and unclear systems often lead to avoidance rather than better decisions.
In daily life, complexity shows up as overlapping subscriptions, unused accounts, and unclear savings goals. Each added layer requires attention and emotional energy. Over time, this can make finances feel unmanageable even when income is stable.
Simplifying systems reduces these barriers. When money flows are clear and predictable, engagement feels safer. This shift supports consistent participation without relying on constant self control.
Moving From Discipline to Decision Architecture
Traditional financial advice often emphasizes discipline and restraint. While discipline has value, it can be hard to sustain alongside work demands and family responsibilities. Decision architecture offers another path by shaping systems so helpful actions happen automatically.
Decision architecture means setting defaults that match long term priorities. Automatic bill payments, scheduled savings transfers, and preselected investment options reduce repeated decisions. These structures keep finances moving even during busy or stressful weeks.
This approach also reduces guilt and self blame. When systems handle routine tasks, missed actions are less personal. Financial care becomes a background process instead of an emotional burden.
Designing a Personal Finance Assembly Line
A finance assembly line treats money movement as a predictable process. Income enters a central checking account and is then distributed to savings, bills, and discretionary spending on set dates. This mirrors organization systems used for email or household tasks.
Using a checking account as a hub improves clarity. Money left after automatic transfers represents true spending flexibility rather than an inflated balance. This reduces accidental overspending caused by unclear signals.
Over time, this structure supports awareness without constant tracking. During the weekly review, confirming transfers is usually enough. The system does most of the work on its own.
Automating Savings and Fixed Costs Safely
Automation removes timing pressure from financial tasks. Scheduled transfers ensure savings and bills are handled consistently. This lowers the risk of missed payments and smooths monthly cash flow.
Savings automation works best when aligned with income timing. Moving money shortly after paydays prioritizes goals before discretionary spending. Many people find this easier than saving whatever remains at the end of the month.
Automating fixed costs like utilities and insurance also reduces effort. During weekly reviews, confirming payments builds trust in the system. Daily attention is no longer required.
Using Defaults for Long-Term Stability
Defaults strongly influence financial behavior. When retirement contributions and reinvestment settings are preselected, people are more likely to stay consistent. This consistency supports gradual progress without emotional decision making.
Many retirement plans use default enrollment and contribution levels. These are commonly associated with higher participation rates. Over time, even modest contributions grow through compound interest when left undisturbed.
Weekly reviews provide a chance to confirm defaults still fit current needs. Adjustments can be made calmly. The simplicity of the system remains intact.
Establishing a Weekly Money Review Routine
A weekly money review is a brief, intentional check in. It usually includes reviewing balances, scanning transactions, and noting upcoming obligations. Keeping it short helps maintain consistency without fatigue.
Many people prefer a calm setting for this review. A familiar time and place supports focus. Treating the review as routine rather than urgent helps normalize financial care.
Over time, this habit builds familiarity. Changes are noticed earlier. This awareness supports steady adjustments without panic.
Monthly and Quarterly Financial Check-Ins
Monthly check ins provide a broader view of spending patterns. These reviews focus on observation rather than judgment. Awareness grows without pressure to correct everything at once.
Quarterly reviews often include net worth updates and investment overviews. This interval balances awareness with emotional steadiness. Frequent monitoring can increase stress without improving outcomes.
Together, these layers create rhythm. Weekly reviews maintain order, while periodic sessions provide context. The system stays balanced and manageable.
Managing Daily Expenses With Minimal Effort
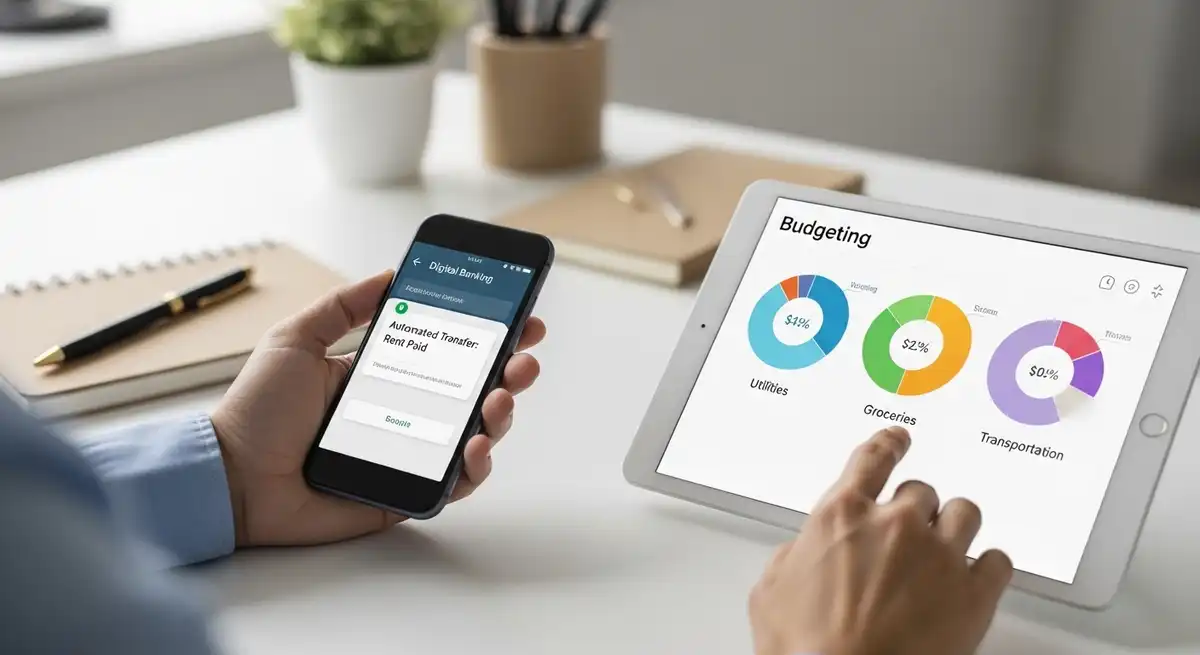
Daily expense tracking becomes easier when done immediately. Recording expenses soon after they occur prevents forgotten details. Many people use simple apps or notes rather than complex spreadsheets.
Accuracy matters more than precision. Approximate amounts are usually enough for awareness. This keeps the habit light and sustainable.
Weekly reviews feel easier when data is already captured. Patterns emerge naturally. Adjustments feel informed rather than restrictive.
The Importance of Consistent Categorization
Consistent categories make spending trends clearer. Using the same labels for similar expenses allows patterns to show over time. Inconsistent labeling often leads to confusion.
Simple categories tend to work best. Broad groups reduce cognitive effort and are easier to maintain. This simplicity supports long term use.
During reviews, category totals provide quick insight. Decisions become clearer. The process feels supportive rather than critical.
Digital Decluttering for Financial Calm
Financial paperwork often creates background stress. Digital organization reduces clutter and improves access. Many tax authorities accept electronic records when stored securely and clearly.
Scanning and naming documents consistently saves time later. Retrieval becomes easier during tax preparation or administrative tasks. Confidence replaces anxiety.
Regular filing fits naturally into weekly routines. Small efforts prevent buildup. The system stays clean and usable.
Understanding Document Retention Guidelines
Knowing what to keep reduces uncertainty. Short term records like receipts are usually kept under one year. Active agreements and titles remain relevant while in use.
Tax documents are commonly retained for several years. Identity and estate records are kept permanently. Clear guidelines support confident decluttering.
During routine reviews, outdated records can be removed. This prevents accumulation. Organization stays manageable.
Choosing a Debt Reduction Strategy
Debt reduction works best when focused. Common methods include the avalanche and snowball approaches. Both prioritize one balance while maintaining minimum payments elsewhere.
The avalanche targets high interest debt to reduce total cost. The snowball targets smaller balances to build momentum. Emotional sustainability often matters more than math alone.
Weekly progress checks reinforce commitment. Visible change builds reassurance. Over time, freed cash flow supports other goals.
Simplifying Investment Portfolios
Simple portfolios often support steadier engagement. Holding a limited number of diversified funds usually provides adequate exposure. Complexity can increase stress without adding value.
Some people separate investments into core and optional segments. The core remains stable. The optional portion allows flexibility.
Reviews focus on alignment rather than performance chasing. Fewer changes reduce emotional reactions. Patience becomes easier.
Building and Protecting an Emergency Fund
An emergency fund provides a buffer for unexpected expenses. Targets vary based on income stability and household needs. Gradual building often feels more realistic.
Keeping emergency savings separate reduces impulsive use. High yield savings accounts are commonly chosen for access and modest growth.
Weekly reviews confirm progress. The fund grows quietly. Reassurance increases over time.
Reviewing and Reducing Recurring Bills
Recurring charges often grow unnoticed. Periodic review helps identify outdated or unused services. This process focuses on alignment, not deprivation.
Insurance and service rates change over time. Brief reviews can uncover savings opportunities. Small changes add up.
Including this step in regular routines prevents buildup. Spending reflects current priorities. Simplicity improves.
Meal Planning as a Financial Support Tool
Food spending is both essential and flexible. Meal planning reduces waste and impulse purchases. Planning around shared ingredients simplifies cooking.
Grocery lists support intentional spending. Entering stores with a plan reduces emotional choices. Many families find this calming.
This habit connects daily life with financial awareness. Consistency grows naturally. The process feels practical.
Understanding the Psychology of Spending
Spending often reflects emotion rather than logic. Stress and fatigue can increase discretionary purchases. Awareness helps without judgment.
Lifestyle creep happens gradually as income rises. Small upgrades reduce savings capacity over time. Noticing patterns supports balance.
Weekly reviews provide space for reflection. Triggers become clearer. Choices feel informed.
Tracking Progress Toward Meaningful Goals
Goals are measurable steps, not vague dreams. Breaking them into smaller targets builds clarity. Progress becomes visible.
Automated tracking tools reduce manual work. Dashboards provide quick snapshots. Reviews stay efficient.
Focusing on direction shifts attention from restriction to purpose. Motivation feels steadier. Pressure decreases.
Parenting and Working Life Considerations
Parents manage finances alongside unpredictable schedules. A one hour routine respects these limits. Predictability supports follow through.
Shared routines improve communication. Clear systems reduce last minute stress. Cooperation improves.
Reduced money stress supports emotional availability. Balance benefits the household. Financial care fits real life.
Frequently Asked Questions
How can I simplify my finances in 30 days?
You can simplify finances in 30 days by setting up automation, organizing accounts, and establishing a weekly review routine. This approach focuses on structure rather than strict budgeting. Many people notice improved clarity quickly once systems replace manual tracking.
What is the 50 30 20 rule for budgeting?
The 50 30 20 rule divides income into needs, discretionary spending, and savings. It is commonly used as a flexible guideline rather than a strict formula. Adjustments are often made based on household size and living costs.
Is the debt snowball or avalanche better emotionally?
The debt snowball often feels motivating because progress is visible early. The avalanche reduces interest costs over time. Choosing the approach that feels sustainable usually matters most.
How long should old financial documents be kept?
Everyday records are usually kept for one year, while tax documents are retained for several years. Identity and estate records are kept permanently. Clear retention habits support organization.
Can finances really be managed in one hour a week?
Many routine tasks can be managed in one hour when systems are automated. The hour focuses on review rather than decision making. This structure supports consistency without daily effort.
Editorial Conclusion
Simplifying finances through a one hour weekly routine brings structure without pressure. Automation, clarity, and predictable reviews reduce cognitive load. This approach supports calmer engagement and aligns money management with everyday responsibilities.
Medical Disclaimer
This content is for informational purposes only and does not constitute medical or mental health advice. It does not diagnose, treat, cure, or prevent any condition. Always consult a qualified professional regarding personal health, mental wellbeing, or financial related stress concerns.
For wider background on this, see the American Psychological Association on stress.