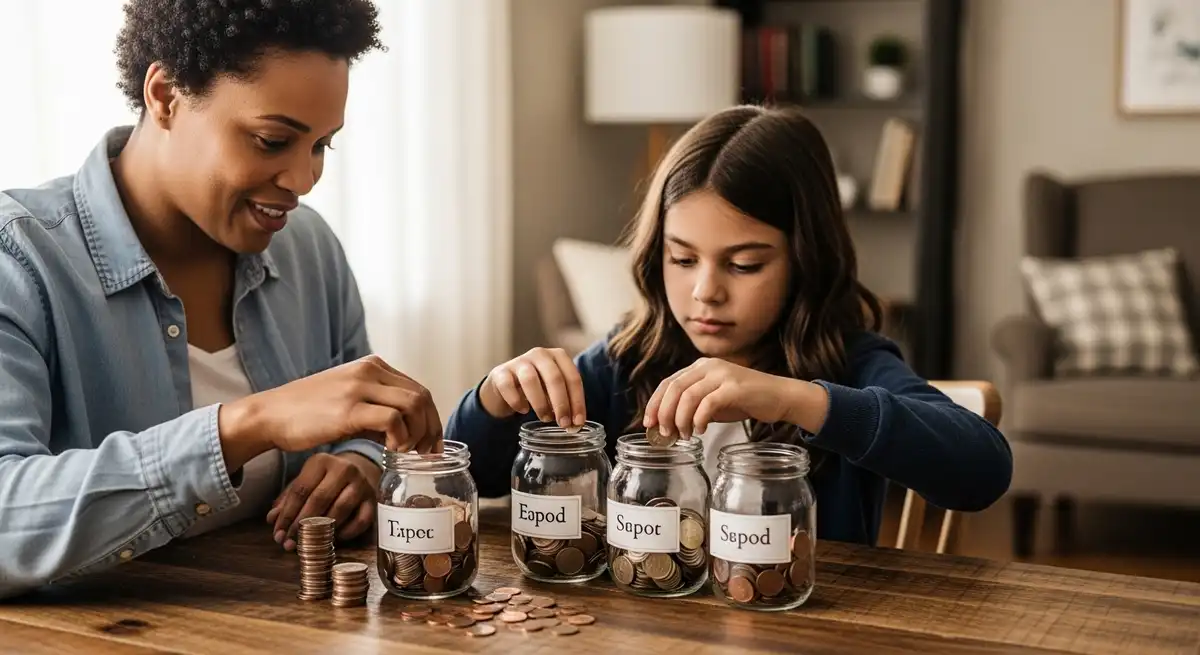
Teaching children about money often begins with counting coins or saving for small purchases, yet the deeper lessons usually come from daily interactions and emotional cues. Children notice how adults respond to spending limits, financial surprises, and planning decisions. A mindful approach focuses on calm explanation, emotional steadiness, and gradual independence, helping children form a practical, balanced relationship with money over time.
Money discussions influence how children understand security, choice, and responsibility in everyday life. When handled with care, these moments support emotional awareness alongside financial skills. This guide explains how to teach kids about money mindfully using realistic, age-appropriate practices that encourage autonomy, patience, and confidence without pressure or fear.
Teach kids money mindfully: Understanding Mindful Money Education in Everyday Family Life
Mindful money education describes teaching financial ideas with attention to emotions, values, and context rather than strict rules or outcomes. Money decisions often carry feelings like excitement, disappointment, or worry, especially for children. Addressing these feelings openly helps children see money as a practical resource instead of a source of tension or status.
In daily routines, mindful money education appears in small, ordinary moments rather than formal lessons. Explaining why a purchase is postponed or how priorities are chosen helps children understand reasoning behind decisions. These explanations reduce confusion and build trust through consistency.
Over time, this approach supports emotional literacy alongside financial understanding. Children learn that money choices involve thinking, waiting, and adapting. These habits often carry into adulthood, where financial decisions frequently intersect with emotions.
The Role of Observation and Money Scripts in Childhood
Children form early beliefs about money through observation, often called money scripts. These beliefs develop as children watch how adults discuss bills, react to expenses, or approach saving. Repeated exposure shapes whether money feels stressful, scarce, or manageable.
Money scripts may reflect avoidance, constant worry, status focus, or idealisation of wealth. Children absorb these patterns quietly, sometimes without direct explanation. Left unaddressed, these beliefs can influence future decisions.
Mindful parents gently bring these patterns into conversation by explaining emotions and plans clearly. A calm explanation of frustration paired with problem-solving helps children separate temporary stress from long-term stability. This openness reduces fear and confusion.
Emotional Regulation as a Foundation for Financial Learning
Emotional regulation is central to learning about money. When adults handle financial challenges calmly, children learn that difficulties can be managed thoughtfully. This modelling shows that emotions do not require immediate reaction.
In everyday situations, emotional regulation may involve pausing before responding to a request or explaining disappointment without blame. These moments teach children that feelings are valid while choices remain flexible. Over time, children become more comfortable with uncertainty.
This skill extends beyond finances into schoolwork, relationships, and personal goals. Children gain confidence in managing disappointment and change. Emotional steadiness supports resilience across many aspects of life.
Building Financial Autonomy Through Guided Independence
Financial autonomy develops when children are allowed to make choices within clear limits. Rather than controlling every decision, mindful education offers opportunities for children to decide how to use small amounts of money. This gradual independence builds understanding without high risk.
Managing a small allowance or savings goal provides practical experience. Children learn that choices involve trade-offs and consequences. These lessons tend to stay with them longer than abstract explanations.
Guided independence also includes reflection after decisions. Talking about what felt satisfying or disappointing encourages learning without judgement. This approach strengthens problem-solving and self-trust.
Internal Locus of Control and Financial Confidence
An internal locus of control reflects the belief that actions influence outcomes. When children practise making financial choices, they begin to feel capable and responsible. Mindful money education supports this belief through consistent guidance.
Children who manage small decisions learn that planning and patience matter. They see themselves as active participants rather than passive recipients. This mindset reduces avoidance and builds adaptability.
Over time, an internal locus of control supports healthier financial behaviour in adulthood. People who feel capable are more likely to plan and adjust. Early guided experiences help establish this confidence.
Teaching Delayed Gratification as a Life Skill
Delayed gratification involves waiting for a desired outcome instead of acting immediately. This skill supports financial stability and emotional balance. Teaching it through everyday money choices keeps lessons practical and relatable.
Simple structures support waiting, such as linking discretionary spending to completed responsibilities. These routines reinforce sequencing rather than punishment. Children learn that waiting is part of decision-making.
Parents who explain their own waiting choices reinforce this lesson. Describing why a purchase is delayed normalises patience. Children see restraint as a shared practice rather than a rule imposed on them.
Supporting Children Who Struggle With Impulsivity
Some children find waiting more challenging due to temperament or developmental stage. Mindful money education recognises these differences without labelling behaviour as a problem. Support focuses on structure and reassurance.
Helpful strategies include shorter waiting periods or visual reminders of goals. Breaking goals into smaller steps allows children to experience progress. These adjustments build confidence gradually.
Calm responses to impulsive moments show children that mistakes are part of learning. This supportive environment encourages persistence. Children learn skills at their own pace.
Distinguishing Needs, Wants, and Personal Values
Understanding the difference between needs and wants helps children prioritise spending calmly. Needs relate to safety and basic wellbeing, while wants add comfort or enjoyment. Clear explanations prevent guilt and confusion.
Using everyday examples keeps lessons grounded. Explaining why certain purchases come first helps children understand limits. Consistency matters more than timing.
Values-based spending acknowledges that priorities differ. Allowing children to choose within limits respects individual preferences. This approach supports thoughtful consumption.
Opportunity Cost and Realistic Decision-Making
Opportunity cost means choosing one option limits another. Introducing this idea early helps children understand trade-offs. Mindful explanations frame it as information rather than loss.
Discussing how one purchase affects future plans connects choices to outcomes. Children learn to weigh options calmly. This supports planning skills.
Over time, understanding opportunity cost encourages intentional decisions. Children become comfortable evaluating options. This perspective reduces regret.
Using Physical Cash to Build Awareness
Physical cash helps children understand limits clearly. Handling money makes spending tangible. This awareness supports reflection.
Seeing cash leave their hands reinforces cost. Counting money slows decisions. These pauses reduce impulsive behaviour.
As children grow, cash can be combined with digital tools. Foundational awareness helps maintain control during transitions.
Jars, Envelopes, and Visual Budgeting Tools
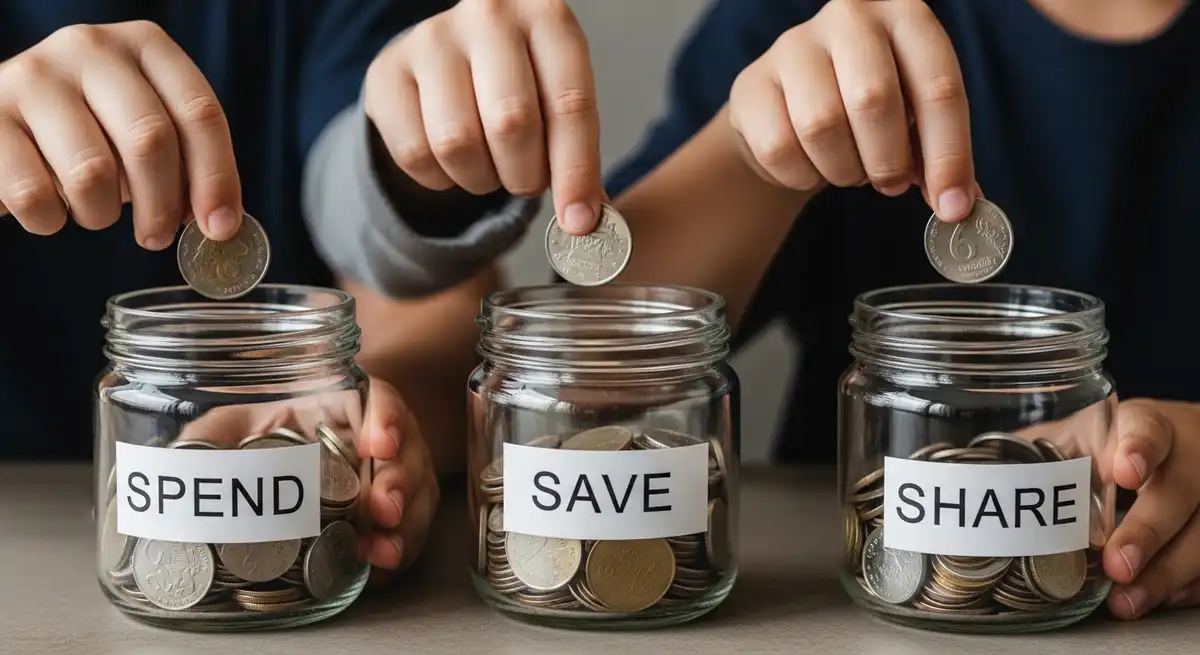
Visual tools like jars organise money by purpose. Categories such as spend, save, and share represent different values. This structure introduces balance.
Seeing money allocated helps children understand consequences. When one jar empties, the result is clear. Accountability becomes natural.
Reviewing tools together encourages collaboration. Conversations focus on patterns. Children internalise budgeting skills.
Spending Logs and the Role of Reflection
Spending logs encourage awareness rather than control. Children track where money goes. Curiosity replaces judgement.
Recording purchases helps children notice satisfaction or regret. Reflection guides future choices. Learning becomes experiential.
Reviewing logs together reinforces insight. Parents highlight trends gently. Analytical skills grow naturally.
Recognising and Managing Spending Triggers
Spending triggers include advertisements, emotions, and peer influence. Mindful education helps children notice triggers. Awareness reduces automatic reactions.
Explaining marketing techniques builds critical thinking. Children learn why products appeal. Desire becomes easier to manage.
Waiting periods help children practise reflection. Over time, selectivity increases. Balanced habits develop.
The Mindful Pause as a Practical Skill
The mindful pause creates space before decisions. In money situations, this pause supports reflection. Children learn to slow down.
Simple actions like breathing or counting interrupt impulses. Reasoning has time to engage. Decisions become calmer.
With practice, pausing becomes automatic. Children carry this skill into other areas. Emotional balance improves.
Setting Realistic and Meaningful Money Goals
Money goals connect present actions to future outcomes. Clear goals prevent frustration. Ownership increases motivation.
Breaking goals into steps shows progress. Small contributions build consistency. Children learn patience.
Goals should reflect the child’s interests. Autonomy encourages engagement. Planning skills strengthen.
Understanding Small Expenses and Money Leaks
Small expenses add up over time. Teaching awareness helps children notice patterns. Discussion remains neutral.
Examples include snacks or digital purchases. Seeing accumulation builds understanding. Budgeting skills improve.
Mindful choices balance enjoyment and awareness. Children decide what feels worthwhile. Intentional spending develops.
Introducing Basic Concepts of Saving and Growth
Saving introduces future planning. Explanations focus on purpose. Children see saving as support, not pressure.
Matching contributions illustrate growth. Consistency matters more than speed. Learning remains educational.
These concepts prepare children for later understanding. Gradual progress feels realistic. Expectations stay balanced.
Parenting and Working-Life Balance in Money Education
Busy schedules can limit formal teaching time. Mindful money lessons fit into daily routines. Small conversations add up.
Consistency matters more than length. Brief explanations repeated over time build understanding. Pressure stays low.
This approach respects family realities. Parents model balance and patience. Children learn by example.
Supporting Emotional Safety in Money Conversations
Emotional safety encourages openness. Children should feel comfortable discussing money. Calm tone builds trust.
Avoiding blame supports learning. Mistakes become feedback. Confidence remains intact.
Over time, money conversations feel normal. Curiosity replaces anxiety. Learning continues naturally.
Frequently Asked Questions
At what age should children begin learning about money
Children can begin learning basic money ideas in early childhood through observation and simple explanation. Early lessons focus on awareness rather than numbers. Gradual introduction supports understanding without pressure.
How can parents explain the value of money without stress
Parents can link money to effort, time, and choice rather than worth. Everyday discussions build understanding. Calm explanations prevent anxiety.
Is allowance necessary for mindful money education
Allowance is one tool among many. Some families use it, others focus on shared decisions. Clarity matters most.
Are chores meant to be connected to money learning
Chores may support responsibility but need not involve payment. Clear explanation prevents confusion. Each family chooses what fits.
How does mindful money teaching differ from traditional budgeting
Mindful teaching emphasises awareness and values. Traditional budgeting often focuses on numbers. Both can coexist.
Can mindful money education reduce impulsive spending
Mindful education supports awareness around spending. Pausing and reflection encourage thoughtful choices. Outcomes vary by child.
What role do parents play in shaping money attitudes
Parents influence beliefs through behaviour and language. Children observe reactions closely. Consistency supports balance.
Is digital money harder for children to understand
Digital money can feel abstract. Many families start with cash. Gradual transition helps understanding.
How can parents address peer pressure around spending
Explaining social influence builds awareness. Discussing values supports confidence. Reflection reduces pressure.
Does mindful money education replace professional financial advice
Mindful money education is informational. It supports habits and awareness. Professional advice may still be helpful.
Conclusion
Teaching kids about money mindfully supports awareness, autonomy, and realistic decision-making. Calm explanation and consistent modelling help children see money as a practical tool rather than a source of stress. Over time, this approach encourages confidence, resilience, and thoughtful financial habits.
Medical Disclaimer
This content is for informational purposes only and does not constitute medical or mental health advice. It is not intended to diagnose, treat, cure, or prevent any condition. Always consult a qualified healthcare or mental health professional for individual concerns or guidance.
For wider background on this, see the American Psychological Association on stress.