If financial boundaries every mom is something you keep putting off, the problem is usually not willpower. It is not having the words ready. Financial responsibility for mothers often carries emotional weight shaped by caregiving roles, family expectations, and long-term security concerns. Money decisions usually affect more than numbers, influencing relationships, routines, and personal confidence. A steady approach to financial boundaries supports stability while allowing care, generosity, and family connection to exist without ongoing stress or quiet resentment.
Financial boundaries are practical limits that help families function over time without constant negotiation. They clarify what is sustainable and what is not, reducing emotional pressure around money. When boundaries are defined, financial choices feel calmer, more intentional, and better aligned with future wellbeing for both parents and children.
Understanding Financial Boundaries in Everyday Family Life
Financial boundaries describe clear limits around spending, saving, and financial support that reflect real capacity. These limits help families understand what can be given without compromising essential needs. In everyday life, boundaries reduce confusion and emotional strain by creating consistency in financial behavior.
Many mothers grow up learning that putting family first means personal sacrifice. Over time, this belief can lead to exhaustion and financial insecurity. Boundaries help reframe financial care as shared responsibility rather than silent self-denial.
Clear limits also improve emotional wellbeing. When expectations are consistent, conversations about money become less tense. This clarity supports respectful communication and helps prevent guilt-driven decisions that undermine long-term stability.
The Role of Emotional Awareness in Financial Decisions
Financial choices often trigger emotions linked to fear, responsibility, or self-worth. Noticing these reactions allows decisions to slow down and become more thoughtful. Emotional awareness does not remove pressure, but it creates room for steadier responses.
Many people associate financial agreement with love or support. This pattern can blur personal limits and increase strain. Separating care from constant financial giving allows support to exist without ongoing depletion.
Wellness educators often note that emotional regulation supports financial consistency. When emotions are acknowledged, spending becomes less reactive. This awareness encourages habits that align with long-term priorities rather than short-term relief.
Financial boundaries every mom: Establishing a Personal Financial Stability Number
A financial stability number represents the minimum level of income and savings needed to meet basic living needs comfortably. This figure usually includes housing, food, utilities, transport, and a modest emergency cushion. Knowing this number provides a concrete reference for financial decisions.
Without a stability number, choices are guided by feelings rather than clarity. This uncertainty increases stress and makes saying no harder. A defined baseline turns vague concern into a clear boundary that protects daily life.
Protecting this number is a foundational financial boundary. It ensures essentials remain secure before additional spending occurs. This approach supports calm decision-making and reduces ongoing anxiety around money.
Moving From Reactive to Responsive Money Management
Reactive money management happens when financial choices are made quickly to ease emotional discomfort. This pattern often appears during family requests or social pressure. While understandable, it can weaken stability over time.
Responsive money management introduces a pause before action. This pause allows review of budgets, priorities, and future plans. Over time, this practice builds confidence and reduces regret.
Simple routines support responsiveness, such as weekly balance reviews. These habits maintain awareness and prevent surprises. Consistent review strengthens boundaries by keeping financial reality visible.
Protecting Baseline Savings Without Guilt
Baseline savings are protective resources rather than optional extras. These funds help manage routine disruptions like job changes or unexpected repairs. Treating them as non-negotiable supports long-term security.
Guilt often arises when savings are protected during family requests. Reframing savings as essential reduces internal conflict. This perspective supports clearer communication and steadier limits.
Protecting savings also models healthy financial behavior for children. It demonstrates planning and foresight. These lessons often influence financial attitudes well into adulthood.
Managing Social and Celebration Spending Thoughtfully
Social spending can quietly erode stability when left unchecked. Celebrations, school events, and gatherings often carry unspoken expectations. Without limits, these costs accumulate gradually.
Celebration capacity refers to the amount of social spending that fits comfortably within a budget. Defining this capacity allows participation without strain. It also prevents resentment linked to overextending.
Thoughtful social spending values connection over consumption. Time and presence often matter more than money. This approach aligns social life with personal values and financial goals.
Distinguishing Presence From Purchase
Presence involves attention, reliability, and shared experience. Purchase-based care relies on material giving. Distinguishing these reduces pressure to overspend.
Research on child development shows emotional security grows from consistency, not gifts. Understanding this supports healthier spending choices. Presence offers meaningful support without financial stress.
Communicating this distinction clearly sets expectations. Over time, families adjust when limits are consistent. This shift supports respect and reduces pressure.
Setting Social Boundaries Without Conflict
Social boundaries work best when expressed early and simply. Clear explanations prevent repeated negotiation. Consistency reinforces trust.
Neutral language focused on personal limits reduces defensiveness. Capacity-based statements feel less judgmental. This approach supports calm dialogue.
Over time, consistent boundaries reduce pressure. Others learn what is possible. This adjustment protects both finances and relationships.
Prioritizing Retirement Planning Responsibly
Retirement planning is essential for long-term family stability. Unlike education, retirement lacks external funding options. Protecting retirement savings prevents future dependence.
Many mothers feel uneasy prioritizing their own future. Cultural messages often discourage self-prioritization. Reframing retirement as family protection supports healthier planning.
Even modest contributions support long-term security through compound growth. Consistency matters more than perfection. This approach reduces future uncertainty.
Balancing Education Support With Financial Limits
Education support remains important for many families. Unlimited funding, however, is rarely sustainable. Clear parameters protect both education goals and retirement.
Common approaches include funding limits or shared responsibility. These strategies balance care with realism. They also promote financial awareness in children.
Early communication reduces later conflict. Discussing expectations allows planning. Transparency supports trust.
Encouraging Shared Financial Responsibility
Shared responsibility teaches practical financial skills. Contributing to education often increases engagement. This involvement supports independence.
Parents can guide without covering all costs. Helping children explore scholarships and budgeting builds competence. These experiences support long-term confidence.
Shared responsibility also protects parental resources. It keeps support sustainable. This balance strengthens family resilience.
Addressing Financial Enabling With Care
Financial enabling occurs when repeated support limits skill development. Intentions are often kind, but outcomes can be harmful. Recognition requires honesty rather than blame.
Signs include repeated requests without progress. Emotional exhaustion often follows. Awareness allows for healthier adjustment.
Shifting from rescuing to encouraging independence supports growth. This change preserves relationships. It aligns care with long-term wellbeing.
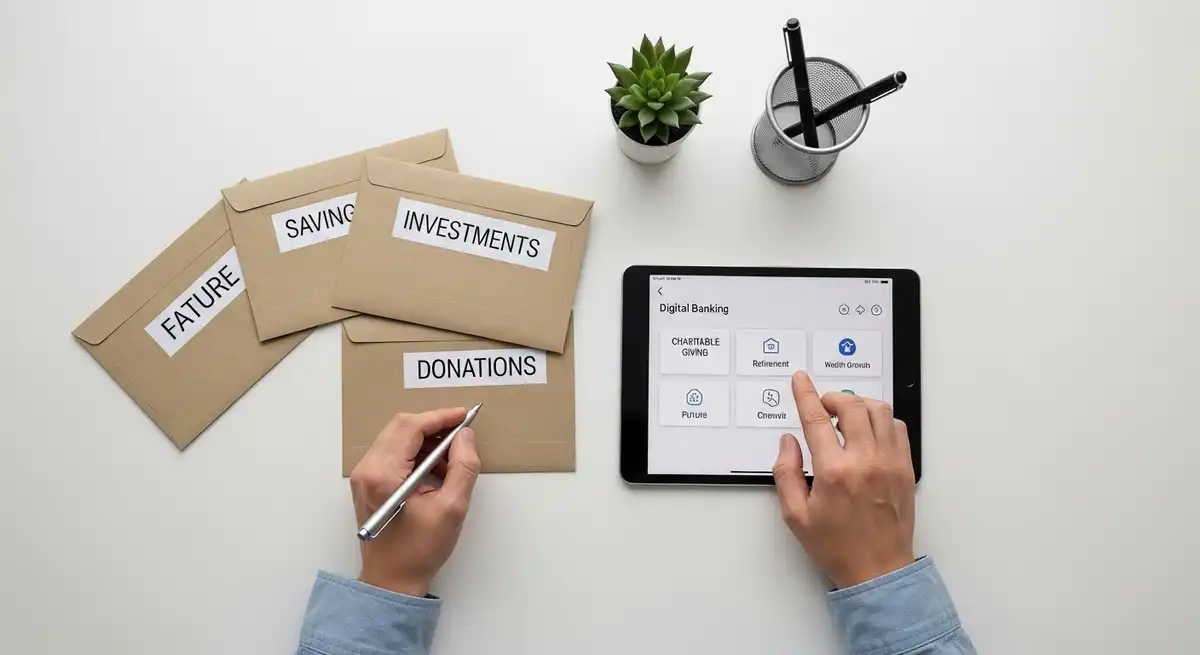
Understanding the Impact of Over-Rescuing
Over-rescuing can reduce problem-solving ability. Automatic help may weaken confidence. This dynamic strains finances and relationships.
Family systems research emphasizes balanced support. Too much help can limit autonomy. Boundaries encourage learning.
Gentle adjustments support change without conflict. Growth occurs alongside connection. This approach respects everyone involved.
Using Structured Support Frameworks
Structured support provides clarity. It defines what help includes and for how long. Structure reduces emotional negotiation.
Timelines and goals support accountability. This clarity protects stability. It also reduces misunderstanding.
Structured support frames boundaries as agreements. This approach strengthens trust. It keeps care aligned with growth.
Creating Payday Check-In Routines
Payday check-ins involve reviewing finances before spending. This habit increases awareness. It supports intentional choices.
Automatic spending hides patterns. A brief pause allows planning. Over time, this routine builds confidence.
Check-ins can be simple. Reviewing balances and upcoming costs is enough. This practice reinforces boundaries.
Recognizing Marketing and Emotional Spending Triggers
Marketing often targets stress or fatigue. Awareness reduces vulnerability. Recognizing patterns supports healthier habits.
Emotional spending provides temporary comfort. It may undermine goals. Pausing helps evaluate real needs.
Non-spending coping options support balance. Rest or connection offers relief. These practices protect finances and wellbeing.
Setting Personal Credit Limits
Credit cards are useful tools when used intentionally. High limits can encourage overspending. Personal limits provide protection.
Lower utilization supports cash flow. It also reduces stress. This approach treats credit as a tool.
Regular balance checks reinforce awareness. This habit supports discipline. Over time, confidence grows.
Understanding the Psychology of Saying No
Saying no often triggers discomfort shaped by social conditioning. Many mothers link refusal with failure. Understanding this reduces internal conflict.
Boundaries support predictability. Consistency strengthens relationships. This stability supports emotional wellbeing.
Calm language normalizes limits. Practice reduces discomfort. This shift supports self-respect.
Unlearning People-Pleasing Patterns
People-pleasing develops as a coping habit. It prioritizes harmony over needs. Over time, it undermines wellbeing.
Unlearning involves noticing limits without judgment. Gradual change supports safety. This approach avoids abrupt shifts.
Practicing boundaries in small moments builds confidence. Success reinforces ability. Over time, skills generalize.
Communicating Needs Clearly
Clear communication reduces misunderstanding. Capacity-based statements avoid blame. This supports respectful dialogue.
Consistency matters more than explanation. Repetition reinforces limits. Pressure decreases.
Clear expression models healthy behavior. Children learn self-respect. These lessons matter.
Financial Boundaries With Adult Children
Relationships evolve as children age. Financial boundaries support this transition. They encourage independence.
Ongoing lifestyle funding creates imbalance. Structured support fosters growth. This balance protects relationships.
Clear agreements manage expectations. Conflict decreases. Respect grows.
Transitioning From Manager to Mentor
Mentorship focuses on guidance. It supports autonomy. This shift matches adult development.
Mentors offer advice without control. Independence grows. Confidence follows.
Transitions take time. Gradual change helps. Trust remains.
Using Third-Party Support When Needed
Neutral third parties offer structure. Advisors provide objectivity. Emotions settle.
Third-party guidance reframes limits as planning. This reduces personal conflict. Clarity improves.
Professional input supports family discussions. Perspective broadens. Boundaries hold.
Managing Extracurricular and Lifestyle Expenses
Activities enrich development but require resources. Over-scheduling strains budgets. Balance matters.
Quality often outweighs quantity. Fewer activities allow depth. Costs stabilize.
Regular review supports alignment. Adjustments are normal. Sustainability improves.
Understanding the Pressure of the Good Parent Narrative
Social narratives equate activity with success. Pressure influences spending. Awareness helps resist comparison.
Children need rest and connection. Balance supports wellbeing. Finances benefit too.
Values guide decisions. Boundaries protect them. Confidence grows.
Protecting Family Energy and Resources
Energy is limited. Overextension affects health. Boundaries protect energy.
Simplified schedules reduce stress. Presence increases. Families benefit.
Resources include time and money. Intentional management matters. Stability improves.
Expanded Guidance on Everyday Mindfulness and Financial Awareness
Mindfulness in finance means noticing patterns without judgment. It supports clarity. This approach is often used as a lifestyle support tool.
Awareness precedes change. Noticing habits creates choice. This principle applies to money.
Simple check-ins support awareness. Automatic behavior decreases. Boundaries strengthen.
Fully Expanded FAQs
How financial boundaries with family are commonly set
Financial boundaries with family are usually set by identifying limits and communicating them calmly. This approach focuses on capacity rather than obligation. Consistent reinforcement allows expectations to adjust over time while relationships remain respectful and stable.
Financial enmeshment and its general effects on children
Financial enmeshment refers to using money to maintain emotional closeness. This pattern can limit independence and confidence. Clear boundaries support skill development while preserving emotional connection.
Retirement savings and education planning balance
Most financial guidance places retirement savings first because alternatives exist for education funding. This priority protects long-term stability. It also reduces future pressure on children.
Communicating reduced financial support to adult children
Reduced support is usually communicated with clarity and compassion. Explaining limits and timelines helps manage expectations. Consistency supports independence.
Saying no to financial requests without guilt
Saying no is a protective boundary rather than rejection. Guilt often decreases with practice. Clear limits support healthier relationships.
Reducing guilt around spending limits
Guilt around limits often reflects learned patterns. Reframing boundaries as care supports ease. Confidence grows with consistency.
Recognizing financial enabling patterns
Financial enabling often shows as repeated support without progress. Awareness allows change. Structured support encourages growth.
Extracurricular costs and family finances
Extracurricular costs add up quickly. Thoughtful selection supports balance. Regular review aligns spending with resources.
Professional support for financial boundaries
Financial professionals help clarify limits. Their neutrality reduces conflict. Guidance supports consistency.
Difficulty saying no to children financially
Difficulty often relates to identity and responsibility. Awareness supports change. Practice builds confidence.
Conclusion
Financial boundaries support stability, clarity, and emotional wellbeing for families. They create structure without rigidity and care without depletion. Thoughtful limits protect present needs and future security while modeling healthy financial behavior across generations.
Medical Disclaimer
This content is for informational purposes only and does not constitute medical or mental health advice. It does not diagnose, treat, cure, or prevent any condition. Consult a qualified healthcare or mental health professional for guidance related to your personal health or wellbeing.
For wider background on this, see the American Psychological Association on stress.